IRS Extends Administrative Relief for 401(k) Plans
As mitigation measures related to COVID-19 ease, it will be interesting to see which practices and regulatory changes taken in response to the pandemic remain in place long-term. One of them might be relief from a sometimes-inconvenient requirement related to the administration of 401(k) plans.
A virtual solution
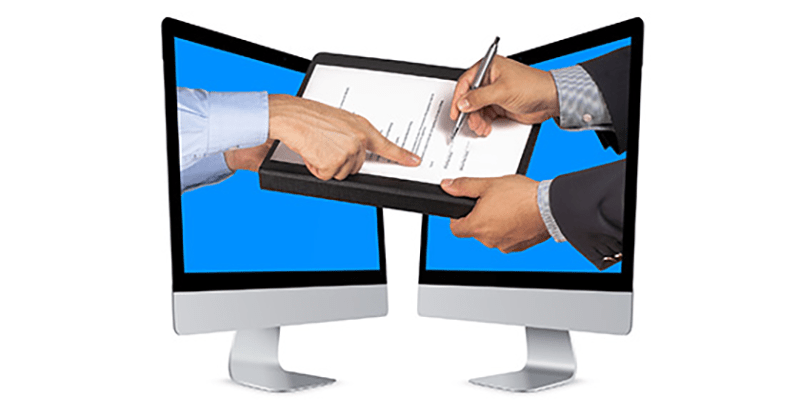
In IRS Notice 2021-40, the IRS recently announced a 12-month extension of its temporary relief from the requirement that certain signatures be witnessed “in the physical presence” of a 401(k) plan representative or notary public.
The original relief, which appeared in IRS Notice 2020-42, was provided primarily to facilitate plan loans and distributions under the CARES Act. However, the relief could be used during 2020 for any signature that, under regulations, had to be witnessed in the physical presence of a plan representative or notary public. This included required spousal consents. The relief was subsequently extended through June 30, 2021, under IRS Notice 2021-03.
Under the notices, signatures witnessed remotely by a plan representative satisfy the physical presence requirement if the electronic system uses live audio-video technology and meets four requirements established under the original relief:
- Live presentation of a photo ID,
- Direct interaction,
- Same-day transmission, and
- Return with the representative’s acknowledgment.
Signatures witnessed by a notary public satisfy the physical presence requirement if the electronic system for remote notarization uses live audio-video technology and is consistent with state-law requirements for a notary public.
Comments requested
As mentioned, IRS Notice 2021-40 further extends the relief — subject to the same conditions — through June 30, 2022. The notice also requests comments regarding whether permanent modifications should be made to the physical presence requirement. Comments are specifically requested regarding:
- The costs and other effects of the physical presence requirement and its temporary waiver,
- Whether the relief has resulted in fraud, coercion or other abuses,
- How the witnessing requirements are expected to be fulfilled as the pandemic abates,
- What procedural safeguards should be instituted if the physical presence requirement is permanently modified, and
- Whether permanent relief should use different procedures for witnessing by plan representatives or notary publics.
Comments should be submitted by September 30, 2021.
More information
Going forward, the need for a signature may often relate to spousal consents. If your business recently established a 401(k), the plan may be designed to limit or even eliminate the need for spousal consents.
However, plans that offer annuity forms of distribution are still subject to the spousal consent rules. And other 401(k) plans must require spousal consent if a married participant wants to name a nonspouse as primary beneficiary.
As always, please do not hesitate to call our offices for additional information and to speak to your representative about how this could affect your situation.
© 2021